UK Water Privatisation: History, Debt & Impact
UK water privatisation from 1989 to 2026: the £4.9bn debt write-off, £60bn+ company debt, rising bills, sewage pollution, Thames Water and who owns it.
Latest Story
In 1989 Margaret Thatcher’s government sold the water and sewerage businesses of England and Wales, writing off their debts and promising that private capital would modernise ageing pipes and treatment works. Thirty-seven years later, UK water privatisation is back at the centre of politics. Companies that started almost debt-free now owe more than £60 billion, Thames Water is kept alive by emergency loans, serious pollution incidents rose 60% in 2024, and bills jumped by a quarter in 2025. Ofwat is to be abolished, and on 29 September 2026 the Prime Minister promised to make public ownership legally easier. This timeline sets out what happened, when, and what the evidence shows.
💡 Short Answer
England and Wales privatised their ten regional water authorities in 1989. The state wrote off about £4.9bn of debt and added a £1.5bn “green dowry”. Investment and drinking-water quality improved, and leakage is 43% lower, but companies built up more than £60bn of debt and pollution incidents rose. In 2025–26 the government moved to abolish Ofwat and, in September 2026, pledged to make public ownership legally possible.
UK Water Privatisation: Key Questions
UK Water Privatisation in Ten Points
- 1974: ten public regional water authorities took over water and sewerage in England and Wales.
- 1989: they were privatised, with about £4.9bn of debt written off and a £1.5bn green dowry.
- 1990s: investment, bills and profits all rose; drinking water and beaches improved.
- 2001: Welsh Water became a not-for-profit company with no shareholders.
- 2006–2017: under Macquarie, Thames Water’s debt rose sharply while it paid large dividends.
- 2010–2015: the NAO found windfall gains of at least £800m that customers mostly did not share.
- 2024: serious pollution incidents rose 60% to 75; Ofwat approved a £104bn five-year plan.
- 2025: bills rose about 26%, Thames got a £3bn emergency loan and a record £122.7m fine; the Cunliffe review called for Ofwat to go.
- 2026: a white paper confirmed a new regulator; ministers rejected the first Thames creditor plan.
- 29 Sep 2026: the PM pledged to make public ownership of water companies legally possible.
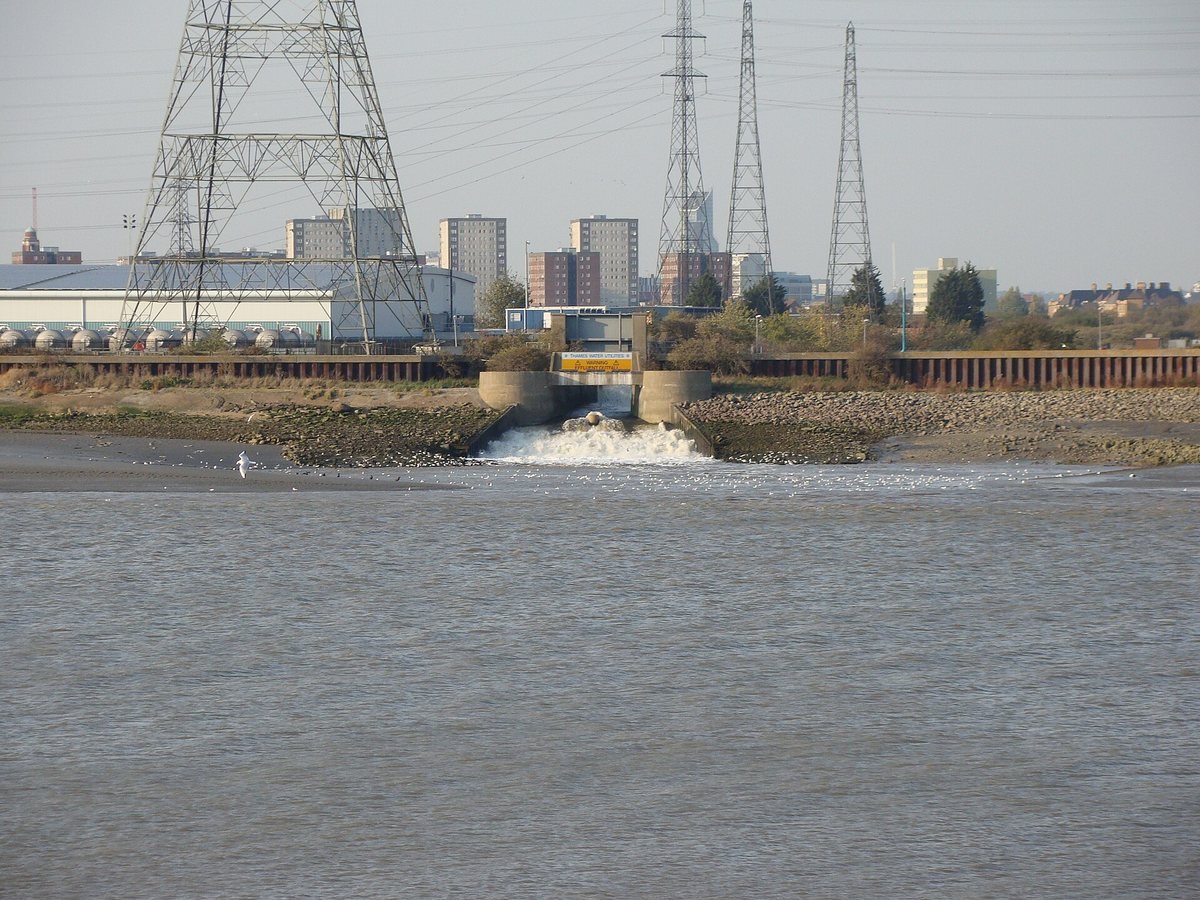
Pick a route for a failing water company
Four options are on the table for Thames Water and any company like it. Tap one to see who bears the cost. Nothing you click is recorded.
Choose a route above
UK Water Privatisation: Full Timeline, 1974–2026
Newest first. Tags show whether a moment is about policy, money, regulation, the environment or Thames Water.
2026
Burnham pledges to lift the “ban” on public ownership Policy
Ten weeks after becoming Prime Minister, Andy Burnham tells Labour’s conference that Environment Secretary Angela Eagle will bring a strengthened Water Bill to Parliament. Its centrepiece is the repeal of what he calls Margaret Thatcher’s “ideological ban” on public ownership of water companies. The bill would also close a loophole used to pay large bonuses and give mayors powers to hold water companies to account. He describes “a 10-year journey to a very different water system” but takes no company into public ownership.
Why it matters: it is the first time a sitting government has said it wants public ownership to be an option. Campaigners said repeal alone does not settle Thames Water; creditors warned of the effect on investment.
Thames creditors prepare a bigger write-off Thames Water
Bloomberg reports on 23 September that the creditor group London & Valley Water, which includes Elliott, Silver Point and Farallon, is preparing a revised offer: a write-down of about 35% of the debt it holds, around £3.5 billion of new equity, and at least £200 million more to settle penalties. In July it had offered the government a “golden share” and a dividend freeze. Thames has warned it could run short of cash by the end of 2026.
Why it matters: the choice is now between a creditor-owned Thames Water on revised terms and a special administration that would put the company under temporary state control.
2026
Ministers refuse to back the £10bn creditor plan Thames Water
Environment Secretary Emma Reynolds says London & Valley Water’s roughly £10 billion recapitalisation does not do enough to protect customers or the environment. More than 100 MPs sign a letter calling for special administration instead. The Commons Environment, Food and Rural Affairs Committee later says the bidders’ priority is to “extract immediate value from Thames Water, not steer it to long-term success”.
Why it matters: it was the clearest sign yet that the government would not simply wave through a creditor takeover.
King’s Speech promises a water reform bill Policy
The King’s Speech includes legislation to create a single, integrated water regulator, bringing together water functions of Ofwat, the Drinking Water Inspectorate, the Environment Agency and Natural England, and a new water ombudsman for complaints.
Why it matters: abolishing Ofwat needs primary legislation. Until it passes, Ofwat remains the economic regulator.
Storm overflow spills fall in a dry year Environment
Environment Agency monitoring data for 2025 shows about 291,000 spills from storm overflows in England, down from about 450,000 in 2024, and total spill time down from about 3.6 million hours to about 1.9 million. The agency says much of the fall reflects the unusually dry weather.
Why it matters: fewer spills are welcome, but rainfall drives the numbers. A wet year could push them back up before the new investment is finished.
2026
White paper: “A new vision for water” Regulation
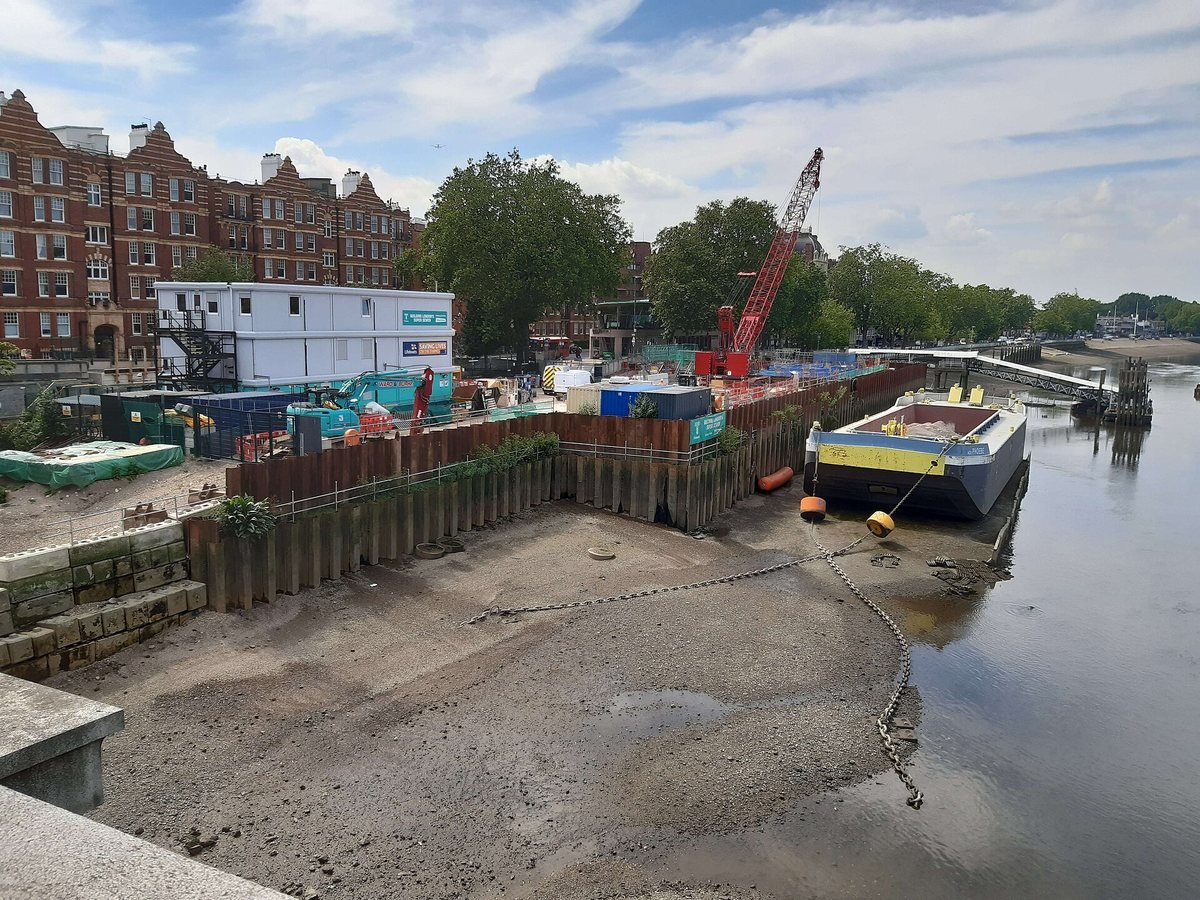
The government publishes its water reform white paper. It confirms that Ofwat will be replaced by a new regulator, with a chief engineer and in-house engineering team, closer supervision of company assets, and tighter rules on ownership and finance. It also covers affordability and planning.
Why it matters: it turned the Cunliffe review into government policy and set the agenda for the next bill.
2025
Worst environmental ratings since 2011 Environment
The Environment Agency’s annual assessment for 2024 finds 75 serious pollution incidents, up 60% from 47 in 2023. Thames Water (33), Southern Water (15) and Yorkshire Water (13) account for 81% of them. The nine English water and sewerage companies earn 19 stars out of 36, down from 25. Only Severn Trent gets the top rating.
Why it matters: the industry had promised to cut pollution incidents by 30% between 2020 and 2025. Instead they rose.
2025
Cunliffe review: abolish Ofwat Regulation
The Independent Water Commission, chaired by former Bank of England deputy governor Sir Jon Cunliffe, publishes 88 recommendations to the UK and Welsh governments. The headline is a single water regulator in England and another in Wales. It also proposes regional water planning authorities, tougher tests on who can own a water company and how much it can borrow, and more help for customers in hardship. Environment Secretary Steve Reed confirms the same day that Ofwat will go.
Why it matters: the review did not recommend nationalisation, but it accepted that the post-1989 regulatory model had failed.
KKR walks away from Thames Water Thames Water
Private equity firm KKR, which Thames had named preferred bidder in March, withdraws. That leaves the company’s senior creditors as the only serious bidder. Ofwat also bans 2024–25 bonuses for executives at several companies with poor pollution records under the new law.
Why it matters: without new outside equity, any rescue would mean lenders taking ownership and losses.
2025
Record £122.7m fine for Thames Water Thames Water
Ofwat imposes its largest ever penalty. It finds Thames failed to operate and maintain sewage treatment works properly, and separately broke its licence rules by paying dividends and executive rewards not linked to performance.
Why it matters: the fine linked the two complaints at the heart of the debate: pollution and payouts.
Bills jump by about 26% Money
The first year of Ofwat’s 2025–30 settlement takes effect. Average household water and sewerage bills in England and Wales rise by about £123, with larger increases for some companies, including Southern Water and Thames Water.
Why it matters: customers began paying for the £104 billion investment plan before most of the projects existed.
Courts approve Thames Water’s £3bn lifeline Thames Water
The High Court sanctions a restructuring plan giving Thames access to up to £3 billion of emergency “super-senior” funding from its senior creditors, at high interest, despite objections from junior creditors and campaigners. The Court of Appeal dismisses challenges in March.
Why it matters: it bought time and avoided immediate special administration, but added expensive debt to a company already owing billions.
2025
Water (Special Measures) Act becomes law Regulation
The new government’s first water law lets the regulator block bonuses at companies that fail environmental, customer or financial standards, toughens penalties for executives who obstruct investigations, and requires real-time monitoring of emergency overflows.
Why it matters: it targeted behaviour inside the existing model rather than ownership itself.
2024
Ofwat approves £104bn for 2025–30 Regulation
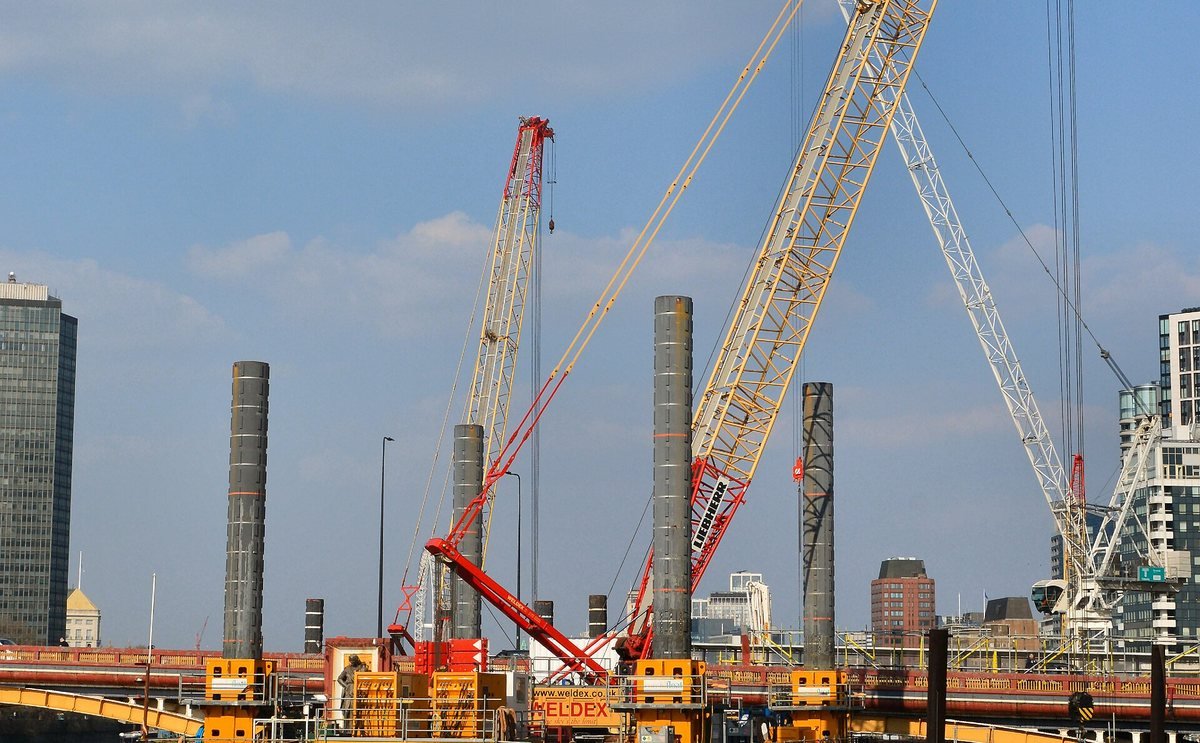
Ofwat’s final determinations for the 2024 price review allow companies to spend £104 billion in five years, roughly double the previous period, including large sums to cut sewage spills and build reservoirs. The July 2024 draft had proposed £88 billion. Several companies later ask the Competition and Markets Authority to redetermine their settlements.
Why it matters: the biggest investment programme since privatisation, funded by customers through bills.
Thames Water placed in special measures Thames Water
Ofwat puts Thames Water into its turnaround regime for failing financial resilience standards, after shareholders refused in March to inject £500 million of promised equity. The new Labour government announces water reforms within weeks.
Why it matters: the shareholders’ refusal ended hopes that the owners would fund a rescue themselves.
Thames Water crisis becomes public Thames Water
Thames Water’s chief executive steps down and reports emerge that the government is preparing for possible special administration. Interest rates are rising fast, and many water company bonds are linked to inflation.
Why it matters: it moved water debt from a specialist concern to front-page news.
Southern Water fined a record £90m Environment
Southern Water pleads guilty to thousands of illegal sewage discharges into rivers and coastal waters in Kent, Hampshire and Sussex and is fined £90 million, then a record for an environmental case.
Why it matters: it showed that discharges were not only accidents of heavy rain but, in some cases, deliberate breaches.
Ofwat targets gearing and complex ownership Regulation
Ofwat chair Jonson Cox criticises highly geared companies, offshore finance structures and opaque ownership. Macquarie sells its last stake in Thames Water in 2017 after an 11-year period in which Thames’s debt rose sharply while it paid substantial dividends.
Why it matters: the regulator acknowledged a problem it had allowed to grow for over a decade.
NAO finds windfall gains of at least £800m Money
The National Audit Office later estimates that companies made net windfall gains of at least £800 million in this price period, because Ofwat assumed higher tax and interest costs than they actually paid. Only part was returned through discounts and investment.
Why it matters: it suggested the regulator was being outmanoeuvred by companies’ finance teams.
Macquarie buys Thames Water Money
An Australian-led consortium buys Thames Water from Germany’s RWE. Over the next decade the company’s debt climbs steeply while shareholders receive large dividends, a period later criticised by academics, MPs and the regulator.
Why it matters: it became the defining example of the financialisation of English water.
Welsh Water goes not-for-profit Money
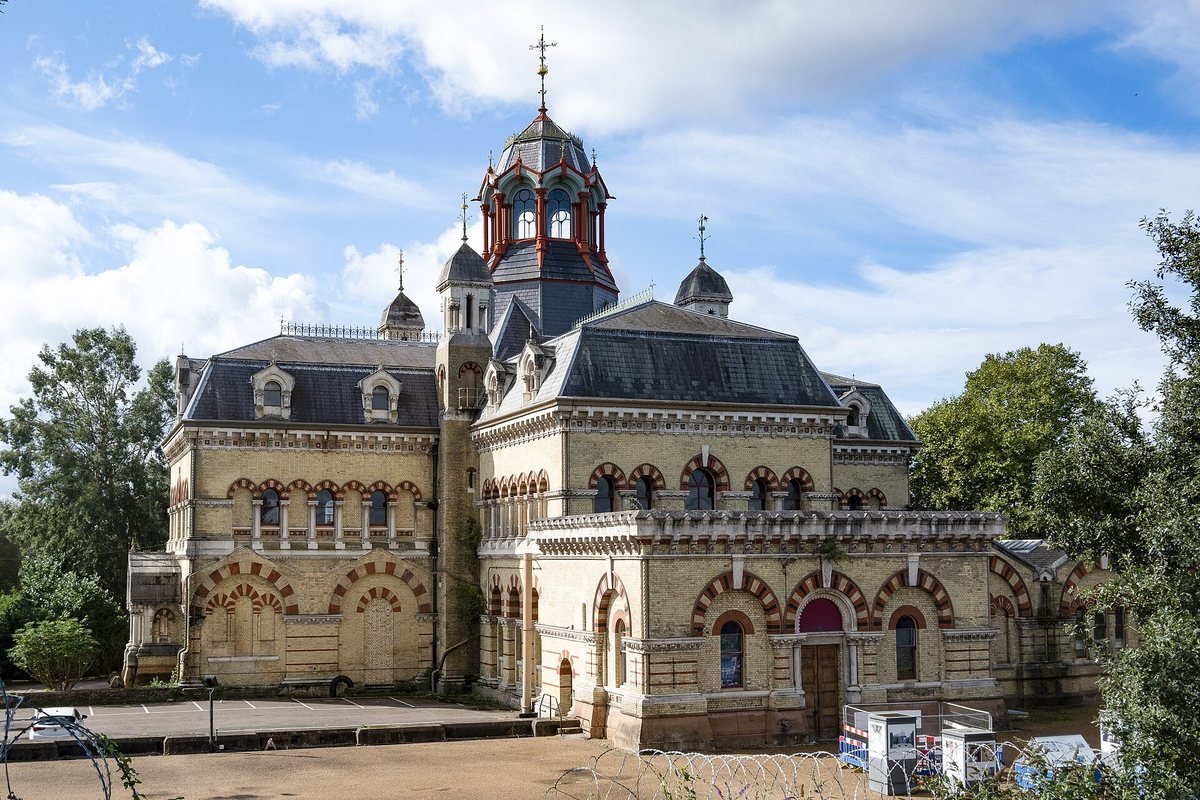
Glas Cymru buys Dŵr Cymru Welsh Water, funding the purchase with bonds. It has no shareholders; surpluses go into the business or customer discounts.
Why it matters: a working alternative model inside the privatised system, though it has its own pollution problems.
Ofwat cuts bills after the 1990s rises Regulation
After a decade in which average bills rose sharply in real terms and profits grew, regulator Ian Byatt orders an average price cut of around 12% from April 2000.
Why it matters: it showed that a regulator could claw back value, though bills climbed again later.
Drought and leakage targets Environment
A severe drought exposes high leakage, especially in Yorkshire, where water is tankered in by road. Mandatory leakage targets follow in 1997.
Why it matters: most of the 43% fall in leakage since privatisation came after this point.
1989
The water industry is privatised Policy
The ten regional water authorities’ businesses pass to new water and sewerage companies, and shares are floated in December. The government writes off about £4.9 billion of debt and adds a £1.5 billion “green dowry”. The same Act creates the National Rivers Authority, the Office of Water Services (Ofwat) and the Drinking Water Inspectorate.
Why it matters: the companies started almost debt-free, which is why the size of today’s borrowing is so controversial.
Privatisation plan, delay and redesign Policy
A 1986 white paper proposes selling the water authorities with their environmental regulation functions. Opposition, including concern that a private company would police its own pollution, delays the plan. It returns after the 1987 election with a separate public regulator for rivers.
Why it matters: the split between private companies and public environmental regulators dates from this redesign.
Ten regional water authorities created Policy
The Water Act 1973 merges many municipal water undertakings, sewerage authorities and river boards into ten public regional water authorities in England and Wales, each covering a river basin. Dozens of smaller statutory water companies stay private.
Why it matters: these ten authorities became the ten companies sold in 1989.
The privatisation settlement in six numbers
Swipe or scroll sideways. These are 1989 figures, not today’s company debts.
Debt written off
The government took on the water authorities’ existing debt.
Money
Green dowry
Cash given to the new companies for early investment.
Money
What the companies were worth
The figure the Commons Library gives for the sale; net proceeds were close to zero.
Money
Companies floated
Anglian, Northumbrian, North West, Severn Trent, Southern, South West, Thames, Welsh, Wessex, Yorkshire.
Policy
New regulators
Ofwat for prices, the National Rivers Authority for pollution, the DWI for drinking water.
Regulation
Monopoly each
Households could not switch supplier, so regulation replaced competition.
Regulation
→ swipe for more
The Debt Question: How Did Water Companies Become So Indebted?
A clean start in 1989
The government took on about £4.9 billion of the water authorities’ debts and gave the new companies £1.5 billion in cash. They began life with little borrowing and a guaranteed customer base. That is the starting point against which today’s debts are judged.
Borrowing is normal; how much is the question
Pipes, reservoirs and treatment works last decades, so spreading their cost through long-term borrowing is standard practice, in public or private ownership. Ofwat’s price controls let companies earn a return on their regulated asset base, which made water company bonds attractive to investors.
The problem was gearing. From the 2000s, several owners added debt at holding-company level to fund acquisitions and dividends, sometimes through offshore structures. Sector net debt passed £60 billion. Many bonds were linked to inflation, so when inflation surged in 2022 the amounts owed rose with it.
Who bears the risk
Shareholders lose first, as Thames Water’s did when they wrote off their investment in 2024. Lenders come next. Customers can pay through bills, and taxpayers through any special administration. A failing company does not mean the taps stop: the special administration regime exists precisely to keep services running.
Five causes, and who is responsible for each
Storm overflows
Treatment works
Farming and roads
Weather and population
Self-monitoring
Only 16% of England’s rivers met good ecological status in the 2019 assessment; none met good chemical status, partly because of tighter tests for long-lasting chemicals.
How Privatisation Has Affected Customers
Bills
Real bills rose substantially in the 1990s, were cut by about 12% in 2000, then climbed again. In April 2025 the average bill in England and Wales rose by about £123 to around £603, and in April 2026 by about £33 to around £639. Water UK says about 2.5 million households get help through social tariffs. Bills pay for operating costs, financing and investment, so a rise cannot be put down to profits or debt alone.
Water quality and leakage
Drinking water compliance is around 99.97%, and Ofwat says leakage is 43% lower than at privatisation. Those are real gains, and most experts credit the investment of the 1990s, driven in part by European water directives.
Service and trust
Customers cannot switch supplier. Ofwat’s 2024–25 performance report found customer satisfaction scores slipping and trust at the lowest level recorded. The planned ombudsman and new regulator are meant to address complaints that companies “mark their own homework”.
The UK already runs four different models
Ownership varies across the four nations. Scroll the table sideways on a phone.
| England | Wales | Scotland | Northern Ireland | |
|---|---|---|---|---|
| Main provider(s) | 9 water and sewerage + water-only companies | Dŵr Cymru Welsh Water (most of Wales) | Scottish Water | NI Water |
| Ownership | Private: funds, pensions, listed firms | Not-for-profit, no shareholders (since 2001) | Public corporation (since 2002) | Government-owned company (since 2007) |
| Dividends | Yes | No | No | No |
| Economic regulator | Ofwat (to be replaced) | Ofwat (Wales to get its own) | Water Industry Commission for Scotland | Utility Regulator |
| Household charges | Bills from company | Bills from company | Collected with council tax | No direct domestic charge |
What changes with ownership, and what does not
| Issue | Private ownership model | Public ownership model |
|---|---|---|
| Access to finance | Borrows from bond markets and raises equity | Public borrowing or public corporation bonds |
| Investment incentive | Regulated returns on assets | Public spending priorities and ministers |
| Accountability | Regulators, boards, courts and investors | Ministers, Parliament, regulators |
| Risk of failure | Shared by shareholders, lenders, customers and, in the end, the state | Sits more directly with public finances |
| Main challenge | Aligning shareholder returns with service and environment | Securing long-term investment against other spending |
These are general features, not guarantees. Scottish Water and Welsh Water have both faced criticism over sewage spills too.
Did Privatisation Work? The Balance Sheet
| Measure | What improved | What got worse or stayed poor |
|---|---|---|
| Investment | Large programmes from the 1990s; £104bn approved for 2025–30 | Underinvestment in sewage works in 2010s, per regulators |
| Drinking water | Compliance around 99.97% | |
| Leakage | 43% lower than in 1989 | About a fifth of treated water still lost |
| Pollution | Bathing water quality improved from the 1990s | 75 serious incidents in 2024, up 60% |
| Finance | Access to bond markets | More than £60bn debt; Thames close to collapse |
| Customers | Social tariffs for about 2.5m households | Bills up about 26% in 2025; lowest trust scores |
Fact Check: Common Claims, Corrected
Checked against the Commons Library, Ofwat, the Environment Agency, the NAO and news reports, up to 10 October 2026.
“The UK privatised its water”
Only England and Wales did. Scottish Water and NI Water are publicly owned, and Welsh Water has had no shareholders since 2001.
“Companies were saddled with debt at privatisation”
The reverse: the state wrote off about £4.9bn and added £1.5bn in cash. The debt came later.
“Water was nationalised after the war”
There was no single post-war nationalisation. The 1973 Act merged many local bodies into ten regional authorities from April 1974; dozens of statutory water companies stayed private.
“Ofwat still has a long-term future”
The government has said since July 2025 that Ofwat will be replaced by a single regulator. It continues until legislation passes.
“Thames Water has been nationalised”
No. As of 10 October 2026 it is still in private hands, with creditors negotiating and special administration an option.
“Falling spills in 2025 prove the problem is fixed”
The Environment Agency attributes much of the fall to an unusually dry year. Serious incidents rose in 2024.
What Happens Next
Thames Water. The government must decide whether to accept a revised creditor plan or seek special administration. The company has warned about cash running short at the end of 2026.
Legislation. A Water Bill is expected to create the new regulator, a water ombudsman and, if the September pledge is kept, a clear legal route to public ownership.
Delivery. The £104 billion plan has to turn into finished projects. The Environment Agency’s next annual assessment, covering 2025, will show whether serious incidents fell.
Explore More Timelines
People Also Ask
Frequently Asked Questions
The Real Question Is Not Only Ownership
The 1989 reform brought in private finance and was followed by real improvements in drinking water and leakage. It also produced a system in which companies could borrow heavily against customers who had no choice, overseen by regulators that most parties now agree were too weak.
Whatever comes next, whether a creditor-owned Thames Water, special administration or a wider move to public ownership, the same tests apply: clean rivers, safe water, affordable bills, and a company that can pay for its pipes.
Related AiTimeline Stories
⚠️ Editorial Note
Last updated 10 October 2026. Figures for 1989 are as given by the House of Commons Library; sector debt and bill figures are rounded. Storm-overflow figures are Environment Agency monitoring data and depend heavily on rainfall. Thames Water’s restructuring is ongoing, and reported creditor terms may change. Quotes from political speeches are attributed and do not represent AiTimeline’s view. The interactive capsule is a simplified guide, not financial or legal advice. Photos are licensed under Creative Commons and credited in captions. Sources are listed below.
Sources & further reading
Every dated entry above was checked against these references. Last reviewed 10 October 2026.
- Water Act 1989 (legislation.gov.uk)
- Water (Special Measures) Act 2025 (legislation.gov.uk)
- Environment Agency - Water and sewerage companies in England: environmental performance report for 2024
- Ofwat - Water Company Performance Report 2024-25
- National Audit Office - The economic regulation of the water sector (2015)
- GOV.UK - A new vision for water: white paper (January 2026)
- GOV.UK - Independent Water Commission final report: roadmap to rebuild trust (July 2025)
- House of Commons Library - Water reform: A new vision for water