Argentina Debt Defaults: A Timeline of Economic Crises, 1982 to 2026
Explore Argentina's debt defaults from 1982 to 2026, including the 2001 collapse, the 2014 bond dispute, the 2020 restructuring and IMF bailouts.
Latest Story
Argentina’s debt defaults are among the most studied in modern finance: the landmark December 2001 default, a technical default in 2014, and a ninth default in May 2020 followed by a roughly US$65 billion restructuring. Between them came IMF programmes in 2018, 2022 and 2025, and under President Javier Milei an austerity drive. This timeline runs newest first, links the IMF, Ministry of Economy and other primary sources in each entry, and keeps a default, a devaluation and a rescheduling separate. Context: the 1971 end of dollar-gold convertibility that ended Bretton Woods shaped the floating-rate world these crises unfolded in.
💡 Short Answer
Argentina’s defining default came in December 2001, about US$95 billion by common estimates. It also defaulted technically in July 2014 and again on 22 May 2020, its ninth default, then restructured about US$65 billion of bonds by August 2020. Since 2018 it has relied on IMF programmes, the latest a US$20 billion facility approved on 11 April 2025 and reviewed in May 2026. No source checked reports a new default in 2026.
Argentina Debt Defaults: Key Questions
Argentina’s Debt Crises in Ten Points
- 2001: the landmark default, about US$95 billion on common estimates.
- Peg: ending the one-to-one peso peg in 2002 was separate from the default.
- 2014: a technical default caused by a US court ruling on holdouts.
- 2016: holdouts settled and US$16 billion raised on 19 April.
- 2018: a US$50 billion IMF Stand-By, enlarged to about US$56.3 billion.
- 2020: ninth default on 22 May, then about US$65 billion of foreign-law bonds restructured.
- 2022: a roughly US$44 billion IMF facility refinanced the 2018 debt.
- 2025: a US$20 billion IMF programme and a US$20 billion US swap line.
- 2026: second review done on 21 May; third review still open in mid-October.
- Test: reserves, inflation, growth and political continuity, not a headline loan.
Argentina Debt Defaults Timeline, Latest First
Each entry is tagged by theme, links primary sources where they exist, and ends with why it matters. Use the filter to isolate defaults, IMF programmes or wider economic events.
Defaults, IMF programmes or the wider economy? Filter the Argentina timeline by theme.
–
Third IMF review is still open as reserves pass US$50 billion IMF programmes
As of mid-October 2026 AiTimeline found no staff-level agreement or Executive Board decision on the third review of the 2025 programme, with an IMF technical mission to Buenos Aires reported in late September. The Rio Times reports that gross reserves closed above US$50 billion on 15 October after the central bank bought another US$182 million, extending a run of purchases to 13 straight days and about US$15.5 billion bought in 2026. The IMF’s May review had noted a missed end-December target for net reserves, which is a different measure from gross reserves. Treat the review outcome as pending until the IMF publishes it.
All three big agencies upgrade Argentina; spreads hit an eight-year low Currency, politics & policy
Reports say Fitch lifted Argentina to B- from CCC+ in May, S&P raised its ratings to B-/B in June, and Moody’s raised it to B3 from Caa1 with a positive outlook, leaving the three agencies aligned for the first time in over a decade (the Moody’s date is reported as July in one source and August in another). MercoPress reported the country-risk spread at 421 basis points on 2 July, the lowest in eight years. Moody’s kept political risk as a key constraint ahead of the October 2027 election. Argentina has not, in the sources checked, returned to international bond markets.
2026
The year’s big bond payment: about US$4.4 billion to Bonares and Globales holders Defaults & restructurings
Argentina owed about US$4.3–4.5 billion in principal and interest on its restructured dollar bonds (reports differ on the exact total). The Treasury said it had the money from its own dollar deposits, multilateral financing from the World Bank and IDB, and a local-law dollar bond (AO28) capped at US$2 billion. Economy Minister Luis Caputo said the government would not tap international markets in 2026. AiTimeline did not find a post-payment confirmation in the sources checked; the Ministry of Economy’s debt page is the place to confirm. The next payment date is 9 January 2027.
2026
IMF completes the second review and releases about US$1 billion IMF programmes
The IMF release says the review unlocked about US$1 billion (SDR 0.8 billion), taking total disbursements under the arrangement to about US$15.8 billion. The IMF said the end-December target for net reserves was missed while most other targets were met, and cited end-period inflation of 117.8% in 2024, 31.5% in 2025 and a projected 25.0% in 2026, with real growth of −1.3%, 4.4% and a projected 3.5%. Corrective measures were under way on reserves.
2026
Argentina pays about US$4.2 billion to private bondholders Defaults & restructurings
The government paid roughly US$4.2 billion in principal and interest on its restructured dollar bonds on 9 January 2026, according to local reports. The restructured bonds pay on 9 January and 9 July each year, so this was the first of the two 2026 payment dates.
2025
Milei’s party wins the midterms; bonds and the peso swing Currency, politics & policy
La Libertad Avanza won about 40.7% of the vote against about 31.7% for the Peronist Fuerza Patria alliance, according to the Konrad-Adenauer-Stiftung (other tallies differ), and rose from 37 to 64 seats in the lower house on government figures. The result beat polls. Wikipedia notes the peso fell about 5% against the dollar and Argentine stocks about 15% afterwards.
2025
The US Treasury finalises a US$20 billion swap line with the central bank Currency, politics & policy
Treasury Secretary Scott Bessent had announced talks in late September. On 9 October the Treasury bought pesos directly and finalised a US$20 billion currency swap line, as reported by AP. Bessent said it was not a bailout and no economic conditions were cited, while critics called it a pre-election reward. Wikipedia reports that Donald Trump tied the support to Milei’s election result; AiTimeline could not confirm that framing from a second source.
2025
A new US$20 billion, 48-month IMF programme IMF programmes
The IMF Executive Board approved a 48-month Extended Fund Facility of US$20 billion (479% of quota), with US$12 billion released immediately. The IMF’s stated aims were entrenching macroeconomic stability, strengthening external sustainability and deepening reforms towards a more open, market-oriented economy. Supporters argued the deficit cuts and tighter monetary financing could stabilise prices; critics warned of costs to households and public services.
Milei’s austerity: surplus on paper, high inflation, a sharp poverty rise Currency, politics & policy
The government cut public spending and aimed for fiscal balance, and reported a financial surplus for the year. The IMF records end-period inflation of 117.8% for 2024 and real GDP growth of −1.3%. Argentina’s statistics agency INDEC put poverty at about 53% in the first half of 2024, the peak of the adjustment, before it fell. This was an attempt to fix the deficits behind earlier crises, not a default.
Milei takes office and devalues the peso by more than half Currency, politics & policy
Javier Milei won the 19 November runoff on promises of radical spending cuts, took office on 10 December, and two days later the government devalued the official peso from about 366 to about 800 per US dollar. Drought had cut agricultural exports, the main source of dollars, earlier in 2023, and usable reserves were thin as the election approached.
2022
Argentina refinances its 2018 IMF debt with a US$44 billion programme IMF programmes
After Congress approved the deal, the IMF Board approved a 30-month Extended Fund Facility worth about US$44 billion, replacing the 2018 Stand-By repayments with a longer schedule and policy targets. It did not erase the debt. The IMF’s own 2021 ex-post evaluation of the 2018 arrangement was critical of how that programme was designed and of its results, which is why 2022 was framed as a rescheduling.
2020
The restructuring closes: 99% of foreign-law bonds exchanged Defaults & restructurings
On 4 August 2020 Argentina announced a deal with three creditor groups on about US$65 billion of foreign-law bonds (Al Jazeera, CNBC); the full US$66 billion figure appears in law-firm notes. On 31 August it reported that 99.01% of eligible bonds were restructured after 93.55% acceptance and the use of collective-action clauses (Marval). A separate local-law exchange followed under Law 27,566 of 8 August. The Ministry of Economy’s debt sustainability page documents the new payment profile. The brief called this about US$100 billion; the foreign-law deal that every major wire quoted was about US$65 billion.
2020
The ninth default: Argentina misses about US$500 million in coupons Defaults & restructurings
After a 30-day grace period expired, Argentina missed roughly US$500 million in interest payments and was widely reported as defaulting for the ninth time in its history (Bloomberg). Its position was that it would not pay until it reached a restructuring deal with creditors. The COVID-19 shock was hitting an economy already in recession. The brief’s draft left this default out entirely.
A primary-election shock, then a “reprofiling” of short-term debt Currency, politics & policy
The primary election result on 11 August showed the opposition well ahead of President Mauricio Macri. The peso lost about a quarter of its value the next day, markets fell sharply, and on 28 August the government announced it would extend maturities on certain short-term debt. Alberto Fernández won the 27 October presidential election. A reprofiling is a debt-management step, and should be kept separate from the formal 2001 default.
2018
A US$50 billion IMF stand-by, later enlarged to about US$57 billion IMF programmes
The IMF Board approved a 36-month Stand-By Arrangement of US$50 billion, with US$15 billion available at once. At the first review on 26 October 2018 it was increased to about US$56.3 billion (US$57 billion in the IMF’s 2021 evaluation, a rounding difference). About US$44.5 billion was ultimately drawn, and the arrangement was cancelled on 24 July 2020 with only four of twelve planned reviews completed. It was the IMF’s largest programme at that point.
Holdouts are settled and Argentina returns to global bond markets Defaults & restructurings
Under President Macri, Argentina announced a US$4.6 billion settlement with NML Capital, Aurelius and other major holdouts on 29 February 2016. Judge Thomas Griesa conditionally dissolved the injunctions on 2 March. Holdouts received more than US$6 billion in April settlements, and on 19 April Argentina sold US$16 billion of bonds, its return to markets after about 15 years. Earlier deals that year, including US$1.35 billion for Italian holdouts, cleared other claims.
2014
A “technical” default over the holdout ruling Defaults & restructurings
US courts had ruled that Argentina could not pay holders of its restructured bonds unless it also paid holdouts under the pari passu clause. Argentina had deposited about US$539 million with the trustee in June to pay the restructured bondholders, but the judge blocked the transfer, and the grace period ended on 30 July. Ratings agencies called it a selective default. Argentina said it had the money and was prevented from paying.
A second exchange lifts participation to about 93% Defaults & restructurings
In 2010 Argentina reopened its restructuring offer for those who had refused the 2005 terms, and total participation rose to about 93%. The remaining holdouts, led by NML Capital, went to court in New York, which set up the 2014 dispute.
The first big exchange: 76% accept, at a deep discount Defaults & restructurings
Roberto Lavagna announced that 76% of bondholders had accepted the restructuring offer, described then as the largest sovereign debt swap in history (Al Jazeera). One analysis says the terms were worth roughly 30 cents on the dollar, with discount bonds cutting principal by about 67%. In January 2006, soon after, Argentina repaid its IMF debt early (about US$9.5 billion).
The peso peg ends and the economy contracts severely Currency, politics & policy
Argentina abandoned the one-to-one peso–dollar convertibility system in January 2002 and let the peso float in February. The peso depreciated sharply, contracts and savings were disrupted, and INDEC’s poverty rate rose above half the population in 2002. Abandoning the peg was a separate event from defaulting on the debt, but both were part of the same collapse.
2001
The landmark default: payments on most public debt are suspended Defaults & restructurings
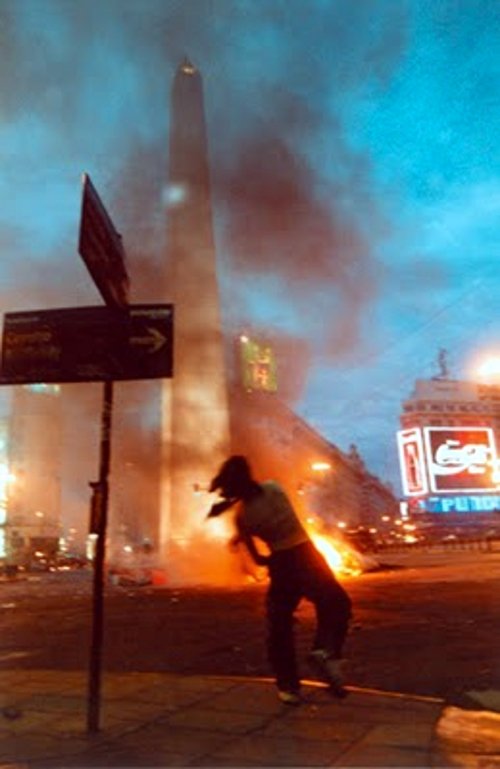
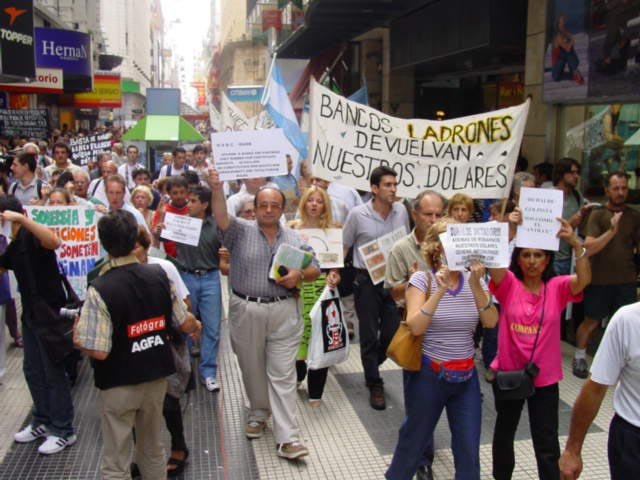
After President Fernando de la Rúa resigned on 20 December 2001 amid protests and a state of siege, interim President Adolfo Rodríguez Saá announced the suspension of payments on most public debt on 23–24 December. Estimates of the amount range widely: about US$80 billion to private creditors plus about US$6.5 billion to the Paris Club in one study, and US$95–100 billion in common press accounts. The cash-withdrawal limits known as the corralito had begun on 1 December. The IMF’s lessons review discusses how the fixed exchange rate and debt dynamics fed the collapse.
Recession exposes the weaknesses of the dollar peg Currency, politics & policy
Argentina entered a prolonged recession in 1998 with the peso tied to the dollar, so it could not devalue to regain competitiveness when the dollar strengthened and Brazil devalued in 1999. Falling activity cut tax revenue and debt rose. In late 2000 an IMF-led support package of about US$40 billion was announced. Investors increasingly doubted the currency regime could last.
Convertibility ties the peso to the dollar; the Brady deal restructures bank debt Currency, politics & policy
The Convertibility Plan fixed the peso at one to the US dollar by law, ended hyperinflation, and restored confidence, and for much of the decade it worked. In 1992–93 Argentina completed a Brady Plan exchange of roughly US$28 billion of commercial-bank debt. Over time the rigid rate left no room to adjust to shocks, which is why the plan is central to debates about 2001.
Hyperinflation destabilises the economy Currency, politics & policy
Prices rose at hundreds of per cent a month at the peak in July 1989, the currency collapsed, and Raúl Alfonsín handed power to Carlos Menem months early on 8 July. It was not itself a sovereign default, but it wrecked confidence in the state’s ability to borrow and repay.
The Latin American debt crisis reaches Argentina Defaults & restructurings
Rising US interest rates, falling export prices and heavy foreign borrowing made foreign-currency debts impossible to service across Latin America in 1982. Argentina’s external debt had grown from roughly US$8 billion in 1976 to around US$45 billion by 1983 under the military government. The crisis began Argentina’s long, repeated relationship with the IMF and with debt rescheduling. Reuters and other outlets count nine sovereign defaults in total since independence, starting in the 1820s.
Three IMF Programmes in Eight Years
How Long Each Default Took to Settle
Inflation Under the 2025 Programme
The Story at a Glance
Dates and figures from the IMF, Argentina’s Ministry of Economy, the World Bank and the news sources listed below.
| Date | Event | Detail |
|---|---|---|
| 1982 | Latin American debt crisis | External debt about US$45bn by 1983 |
| 1989 | Hyperinflation | Menem takes office early on 8 July |
| 1991 | Convertibility | Peso fixed one to one with the dollar |
| 1998–2001 | Recession | Dollar peg limits adjustment |
| 23 Dec 2001 | Default | About US$95bn (estimates vary) |
| Jan–Feb 2002 | Peg ends | Peso floats from 11 Feb |
| Mar 2005 | First exchange | 76% accept; roughly 30 cents on the dollar |
| 2010 | Second exchange | Participation about 93% |
| 30 Jul 2014 | Technical default | Holdout ruling blocks payment |
| Apr 2016 | Holdouts settled | US$16bn bond sale 19 Apr |
| 20 Jun 2018 | IMF Stand-By | US$50bn, later about US$56.3bn |
| 22 May 2020 | Ninth default | About US$500m coupons missed |
| 31 Aug 2020 | Restructuring | About US$65bn of foreign-law bonds; 99.01% restructured |
| 25 Mar 2022 | IMF refinancing | About US$44bn, 30 months |
| Dec 2023 | Milei takes office | Peso devalued about 54% on 12 Dec |
| 11 Apr 2025 | IMF programme | US$20bn, 48 months |
| 9 Oct 2025 | US swap line | US$20bn with the central bank |
| 21 May 2026 | IMF second review | About US$1bn; US$15.8bn disbursed in total |
| 9 Jul 2026 | Bond payment | About US$4.4bn due; settlement to verify |
Why Has Argentina Defaulted So Often?
1. Foreign-currency debt. When obligations are in US dollars but revenue is collected in pesos, a sharp depreciation makes the debt harder to service. The World Bank’s International Debt Statistics track Argentina’s external debt stocks.
2. Weak reserves. Argentina earns dollars mainly from agricultural exports. A drought, capital outflows or lost market access can leave it short, as the IMF’s May 2026 note on a missed net-reserves target illustrates.
3. Inflation and currency instability. Persistent inflation erodes confidence in the peso and drives demand for dollars. For another currency collapse see the Turkish lira crisis and Lebanon’s financial collapse; savers elsewhere who distrust fiat money sometimes look to scarce digital assets, covered in our Bitcoin halving price history.
4. Fiscal and financing gaps. When spending outruns revenue and sustainable borrowing, governments cut, tax, seek help or restructure.
5. Political uncertainty. Policy reversals make investors doubt that commitments will survive an election; Moody’s still lists the October 2027 vote as a key risk.
6. The cost of adjustment. Stabilisation can cut inflation, but spending cuts and devaluation hit household incomes, and that makes reforms hard to sustain.
For the wider pattern, see our worldwide inflation and economic crises timeline.
| Term | Meaning | Why it matters here |
|---|---|---|
| Sovereign default | A government fails to meet the terms of a debt obligation | The 2001, 2014 and 2020 episodes differ in cause and scale |
| Selective / technical default | A rating agency’s label when some bonds go unpaid, often over a legal dispute | Used for July 2014, when a US ruling blocked payments |
| Holdouts | Creditors who refuse a restructuring offer and sue for full payment | The 2005 and 2010 refusers drove the 2014 dispute |
| Pari passu clause | Promise to treat creditors equally | US courts read it to bar paying exchange bondholders alone |
| Collective action clause (CAC) | Lets a supermajority bind a minority to a restructuring | Helped push 2020 acceptance past 99% |
| Corralito | Limits on cash withdrawals from December 2001 | Triggered mass protests |
| Convertibility | The 1991–2002 one-to-one peso–dollar fixed rate | Central to the 2001 collapse |
| Extended Fund Facility (EFF) | IMF loan for deeper structural problems, repaid over a longer term | The 2022 and 2025 programmes |
| Stand-By Arrangement (SBA) | IMF loan for short-term balance-of-payments problems | The 2018 programme |
| Riesgo pais | JP Morgan EMBI spread over US Treasuries, in basis points | Fell to 421 bp on 2 Jul 2026 |
Is Argentina in Default in 2026?
What the evidence shows. A country can have restructured some debt, keep paying other debt, and negotiate IMF money at once. As of 21 October 2026 AiTimeline found no report of a missed payment: the January payment of about US$4.2 billion was reported paid, funding for about US$4.4 billion due on 9 July was arranged, the IMF released US$1 billion in May, and the three big agencies raised the rating this year.
What is not established. A post-payment confirmation of the July settlement was not found, the IMF’s third review was still open in mid-October, and the May review noted a missed net-reserves target. None of this proves a default is coming, and none of it proves the risk has gone.
How to check. Use the Ministry of Economy’s debt sustainability page, the IMF’s latest review and the World Bank’s debt data. The next bond payment date is 9 January 2027.
Who Is Who in the Story
Javier Milei
Took office on 10 December 2023 and led the austerity programme and the 2025 IMF deal.
Luis Caputo
Runs debt payments and told reporters the government would not tap international markets in 2026.
Scott Bessent
Announced and finalised the US$20 billion swap line in September–October 2025.
Adolfo Rodríguez Saá
Announced the suspension of payments in December 2001.
Thomas Griesa
US District Court judge in the holdout case that led to the 2014 technical default.
Roberto Lavagna
Led the first exchange in which 76% of bondholders accepted.
Mauricio Macri
Settled with holdouts in 2016 and signed the 2018 IMF Stand-By.
NML Capital
Holdout fund whose court cases dominated the 2012–16 dispute.
What Argentina’s Debt History Teaches
Breathing room is not a cure. IMF loans and exchanges buy time. Durable recovery needs sustainable public finances, credible money, enough dollar earnings, manageable repayments and growth.
Legal design matters. The 2005 exchange left a holdout minority that blocked payments for years; the 2020 deal used collective-action clauses to reach 99%.
The wider monetary order. Argentina’s peg and floats unfolded after the system built at Bretton Woods ended; see how the US ended the gold link in 1971.
The Popular Story vs the Record
| Popular version | What the record shows |
|---|---|
| Argentina defaulted once, in 2001 | Coverage counts nine defaults since independence; 2014 was a technical default and May 2020 a negotiated one, plus earlier episodes |
| The 2020 restructuring covered US$100 billion of bonds | Reuters, Bloomberg and Al Jazeera put the foreign-law deal at about US$65 billion, with a separate local-law exchange |
| The IMF’s 2025 loan is US$20 billion in cash | It is a US$20 billion ceiling over 48 months; about US$15.8 billion had been disbursed by May 2026 |
| A new IMF review means no default risk | The IMF release itself notes a missed net-reserves target; ratings upgrades reduce, not remove, the risk |
| Devaluation and default are the same | Devaluation is a falling currency; default is a missed debt payment. 2001 and 2002 had both, but they are separate events |
| The 2014 default meant Argentina had no money | It had deposited about US$539 million; a US court blocked the transfer to restructured bondholders |
| Austerity alone produced the 2024–26 recovery | Disinflation, a US swap line, IMF money and ratings upgrades all contributed; no single cause is established |
| Argentina is back on international markets | In the sources checked it has not issued an international bond in 2026, and its minister said it would not |
Argentina’s Debt in Numbers
| Measure | Figure | Source and caveat |
|---|---|---|
| 2001 default amount | About US$95bn (US$80bn–100bn+ depending on count) | Press accounts and academic studies; depends on interest and instruments |
| 2005 exchange acceptance | 76% | Al Jazeera, Mar 2005 |
| 2010 total participation | About 93% | CADTM and legal summaries |
| 2016 holdout deal | US$4.6bn main settlement; over US$6bn paid in April | Court-appointed master and press |
| 2018 IMF programme | US$50bn, about US$56.3bn after increase | IMF; US$57bn in the IMF 2021 evaluation |
| 2020 restructuring | About US$65bn of foreign-law bonds | Reuters, Al Jazeera; US$66bn in legal notes |
| 2020 acceptance | 99.01% restructured | Marval, 31 Aug 2020 |
| 2022 IMF programme | About US$44bn, 30 months | IMF |
| 2025 IMF programme | US$20bn, US$12bn upfront | IMF release 25/101 |
| Disbursed by May 2026 | About US$15.8bn | IMF release 26/165 |
| Inflation 2024 / 2025 | 117.8% / 31.5% | IMF, end-period |
| Gross reserves | Above US$50bn on 15 Oct 2026 | Rio Times; gross, not net |
| July 2026 bond payment | About US$4.3–4.5bn | Reports differ; verify with Ministry |
Explore More Timelines
People Also Ask
Frequently Asked Questions
Related AiTimeline Stories
⚠️ Editorial Note
Last updated 21 October 2026. Facts were checked against the IMF press releases of 11 April 2025 and 21 May 2026, IMF documents on the 2018 programme, Argentina’s Ministry of Economy debt page, Reuters, Bloomberg, Al Jazeera, CNBC and AP coverage of 2020 and 2025, law-firm summaries, and local reports for 2026 payments. Amounts are approximate and vary by whether a figure is bond principal, claims, a commitment or actual disbursements. An IMF approval is not money disbursed, and a restructuring is not a new default. Corrections to the draft brief: the May 2020 default was missing; the 2020 restructuring was about US$65 billion of foreign-law bonds (not US$100 billion); the 2018 programme was US$50 billion at approval and about US$56.3 billion after October; a cited Reuters URL could not be verified and was dropped; and the 2001 total ranges from about US$80 billion to over US$100 billion depending on the count. The IMF’s third review and the July 2026 settlement are unconfirmed as of this date.
Sources & further reading
Every dated entry above was checked against these references. Last reviewed 21 October 2026.
- IMF: Argentina Executive Board approves 48-month US$20 billion Extended Arrangement (11 Apr 2025)
- IMF: Argentina completes second review of the Extended Arrangement (21 May 2026)
- IMF: Lessons from the Crisis in Argentina
- IMF: Executive Board approves Stand-By Arrangement for Argentina (June 2018)
- Ministry of Economy: Debt sustainability
- World Bank: International Debt Statistics, Argentina
- Argentina reaches deal with creditors to restructure $65bn debt
- Marval: foreign-law debt exchange closes, 99% of bonds restructured
- US buys Argentine pesos, finalizes $20 billion currency swap