Silicon Valley Bank Collapse Timeline: The 48-Hour Run That Shook Banking
Silicon Valley Bank collapse timeline: the $1.8bn loss on 8 March 2023, the $42bn run, closure on 10 March, the rescue, and what the Fed found in 2026.
Latest Story
On the evening of 8 March 2023, the bank that served America’s startups announced a $1.8 billion loss and a plan to raise capital. By late morning on 10 March it was gone. The Silicon Valley Bank collapse was the second-largest bank failure in US history at the time, and the fastest bank run on record: customers asked for about $42 billion in a single day. This timeline follows the 48 hours hour by hour, the rescue that protected every depositor, and what courts and a new Federal Reserve review have found since, including the September 2026 conclusion that social media did not cause the run.
💡 Short Answer
Silicon Valley Bank collapsed on 10 March 2023, when California regulators closed it and appointed the FDIC as receiver. Two days earlier it had announced a $1.8 billion loss on bond sales and a $2.25 billion capital raise; on 9 March customers, mostly startups with uninsured deposits, asked to withdraw about $42 billion. Regulators protected all depositors on 12 March and First Citizens bought the bank’s deposits and loans on 26 March.
Silicon Valley Bank Collapse: Key Questions
The SVB Collapse in Ten Points
- 48 hours: from an 8 March 2023 announcement to closure on 10 March.
- Record run: about $42 billion requested on 9 March, a quarter of deposits; over $100 billion more was queued.
- Rate risk: about $15 billion of unrealized bond losses by end-2022, roughly its entire equity.
- Uninsured: about 94% of deposits were above the $250,000 limit.
- Concentrated: startups and VC funds shared investors, advice and the same cash squeeze.
- Not ready: SVB had not tested discount-window borrowing.
- Full rescue: every depositor protected on 12 March; shareholders wiped out.
- Sold: First Citizens bought deposits and loans on 26 March; FDIC cost about $20 billion.
- Courts: the FDIC is suing 17 former leaders; a judge ruled in August 2026 the run was ‘foreseen’.
- New verdict: the Fed’s 2026 review says supervisors knew by March 2022 and social media did not trigger the run.
Silicon Valley Bank Collapse at a Glance
Figures refer to different dates and measures. Scroll sideways on a phone.
| Detail | Key fact | Source |
|---|---|---|
| Bank | Silicon Valley Bank, Santa Clara, California (founded 1983) | Federal Reserve |
| Parent | SVB Financial Group (Chapter 11 from 17 Mar 2023) | Bankruptcy court |
| Customers | Venture-backed tech and life-science firms, VC funds | Federal Reserve |
| Assets, end-2022 | ~$209 billion (bank); ~$212 billion (group) | FDIC; Federal Reserve |
| Deposits, end-2022 | ~$175.4 billion; ~94% uninsured | FDIC; Federal Reserve |
| Trigger | 8 Mar 2023: $21bn securities sold, $1.8bn loss, $2.25bn raise | SVB Financial Group |
| Run | ~$42bn requested on 9 Mar; $100bn+ expected 10 Mar | California DFPI; Fed |
| Closed | 10 Mar 2023; FDIC receiver | FDIC |
| All depositors protected | 12 Mar 2023, systemic-risk exception | Treasury, Fed, FDIC |
| Buyer | First Citizens, 26 Mar 2023 (~$72bn assets, $16.5bn discount) | FDIC |
| Cost to FDIC fund | ~$20bn (first estimate) | FDIC |
| Latest | Fed-commissioned review, Sep 2026; supervision overhaul, Oct 2026 | Federal Reserve |
Timeline: From a Startup Bank to the 48-Hour Run and After
Newest first, from October 2026 back to 1983. Tags mark risks, the run, events, rescues, reviews, court cases and 2026 developments.
The Fed reorganises supervision 2026
On 6 October Federal Reserve Vice Chair for Supervision Michelle Bowman announced that bank supervision would be regrouped into five geographic regions, each with a single regional leader, following state lines rather than Reserve Bank districts. She cited the independent SVB review’s finding that examiners were slow to act because no one clearly owned the decision.
Senator Elizabeth Warren opened an inquiry into reports that private parties saw the Fed-commissioned SVB report before its public release, a sign that the politics of the failure are not over three and a half years later.
2026
An independent review rewrites the story Review
Bowman presented the first findings of the review she commissioned from Starling Advisory Group. Its conclusions: Fed staff knew, or should have known, of SVB’s vulnerabilities as early as March 2022, a year before it failed; a long-standing culture of risk aversion made examiners feel safer doing nothing than acting and being wrong; and the 2018 ‘tailoring’ law that eased rules for mid-sized banks did not cause the delays.
Most strikingly, an analysis by Charles River Associates for the review found that social media did not trigger the run: 96% of social media chatter about it appeared after SVB’s failure was already inevitable. The report was published as a public exposure draft on 21 September, with further reports to come.
2026
A judge says the run was ‘foreseen’ Court
In the long fight between the FDIC and SVB’s former parent over cash it held at the bank, a federal judge ruled the FDIC does not have to hand back $1.71 billion. She found that officers of both the holding company and the bank breached their fiduciary duties by loading the bank with interest-rate and liquidity risk, removing partial hedges, and approving a $294 million dividend to the parent in December 2022 while the bank was in ‘dire financial condition’.
‘The evidence presented at trial established that the risk of a bank run was not only foreseeable but in fact foreseen,’ Judge Freeman wrote.
2025
The FDIC sues 17 former leaders Court
The FDIC, as receiver, sued six former officers and 11 directors for gross negligence and breach of fiduciary duty, calling SVB ‘a case of egregious mismanagement of interest-rate and liquidity risks’. It alleged they bought long-dated, unhedged securities, changed risk-model assumptions to hide limit breaches and paid the parent a ‘grossly imprudent’ dividend.
In October 2025 Judge Noël Wise of the Northern District of California refused to dismiss the case. It was still pending in October 2026.
2024
Emergency lending ends Rescue
The Bank Term Funding Program, created the weekend SVB failed, stopped taking new loan requests on 11 March 2024, as the Fed had announced in January. It had let banks borrow for up to a year against Treasury and agency securities valued at par, not at their depressed market price, removing the forced-sale trap that sank SVB.
Aug 2024
Paying the bill and winding down Rescue
To recover what it spent protecting uninsured depositors at SVB and Signature Bank, the FDIC adopted a special assessment of about $16.3 billion, charged mostly to the largest banks rather than to taxpayers or small community banks.
SVB’s former parent, which filed for Chapter 11 bankruptcy on 17 March 2023, had its plan approved in August 2024, leaving SVB Financial Trust to pursue a claim of about $1.9 billion against the FDIC.
2023
The Fed blames itself, too Review
The Federal Reserve’s review, led by Vice Chair for Supervision Michael Barr, found that SVB’s board and management failed to manage basic interest-rate and liquidity risk, that supervisors did not fully appreciate the vulnerabilities as the bank grew, and that when they did identify problems they did not push hard enough. It also argued that the post-2018 shift to lighter rules for mid-sized banks contributed.
It noted SVB had not tested its ability to borrow from the discount window and lacked the collateral arrangements to do so quickly. California’s regulator published its own review days later.
2023
Contagion: First Republic falls Risk
SVB’s failure set off weeks of bank stress. New York regulators closed Signature Bank on 12 March. In Europe, Credit Suisse was taken over by UBS on 19 March. In the US, First Republic Bank, another lender with many uninsured, wealthy depositors, was seized on 1 May and sold to JPMorgan Chase.
2023
First Citizens buys the bank Rescue
The FDIC agreed to sell Silicon Valley Bridge Bank’s deposits and loans to First-Citizens Bank and Trust Company of Raleigh, North Carolina. First Citizens bought about $72 billion of assets for a $16.5 billion discount, with a loss-share agreement on commercial loans, and received equity appreciation rights worth up to $500 million to the FDIC.
About $90 billion of securities and other assets stayed in receivership. The FDIC estimated the cost to its insurance fund at about $20 billion.
2023
The bridge bank opens Rescue
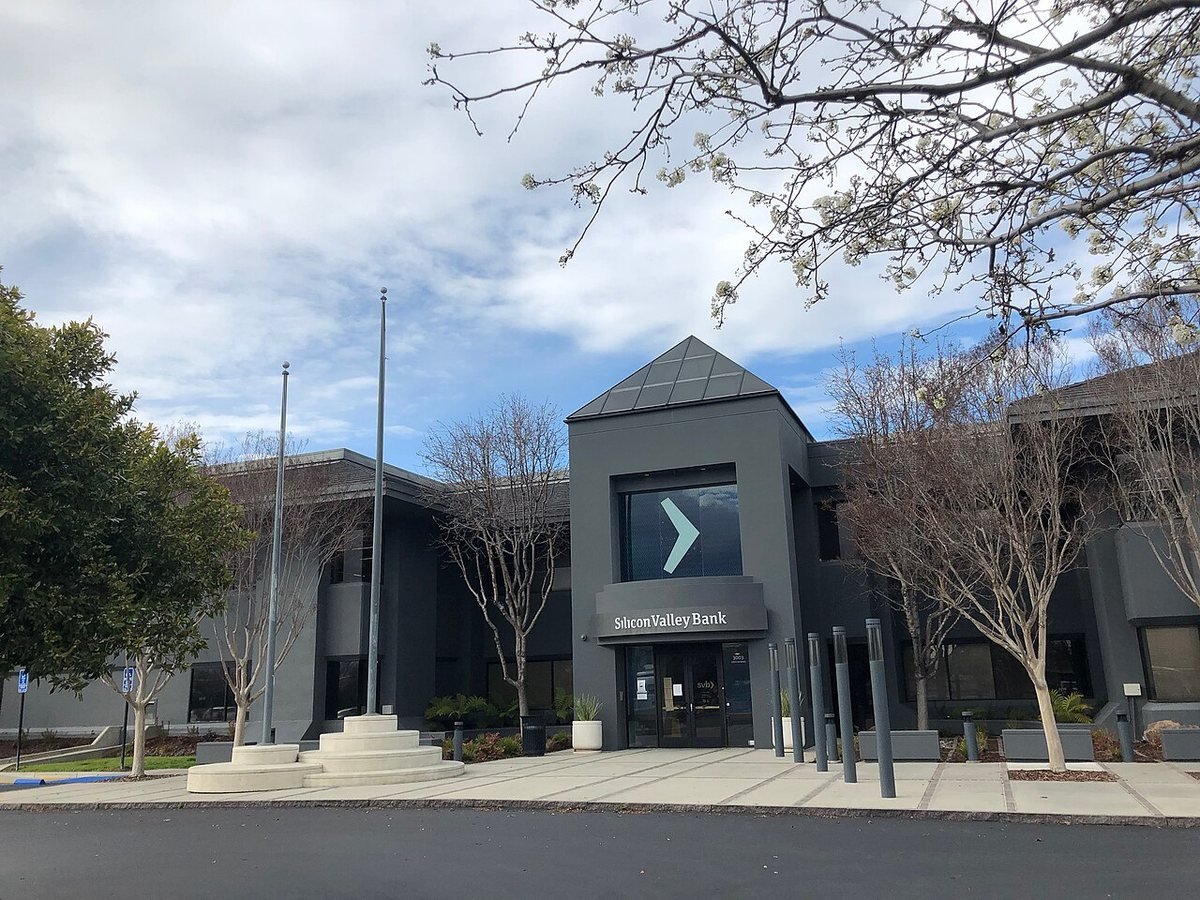
On Monday morning SVB’s offices reopened as Silicon Valley Bridge Bank, a temporary national bank run by the FDIC. All deposits and substantially all assets moved across, and customers could access every dollar. Many moved money out anyway, to big banks they considered too big to fail.
2023
Washington protects every depositor Rescue
On Sunday evening, before Asian markets opened, Treasury Secretary Janet Yellen, Fed Chair Jerome Powell and FDIC Chair Martin Gruenberg said depositors at SVB, and at Signature Bank, closed the same day, would have access to all their money from Monday. The systemic-risk exception covered deposits above the $250,000 limit.
Shareholders and some unsecured debt holders were not protected, and senior management was removed. The Fed also launched the Bank Term Funding Program so other banks could borrow against their bonds without selling them.
2023
Closed by mid-morning Event
On the morning of 10 March, before the queued withdrawals could be paid, the California Department of Financial Protection and Innovation closed Silicon Valley Bank and appointed the FDIC as receiver. The FDIC put insured deposits into a new Deposit Insurance National Bank of Santa Clara and promised uninsured customers an advance dividend.
At the end of 2022 SVB had about $209 billion in assets and $175.4 billion in deposits, making it the second-largest US bank failure at the time, after Washington Mutual in 2008.
2023
$42 billion in one day Run
As SVB’s share price collapsed, venture-capital firms advised portfolio companies to move their cash, and founders did, using online banking to send money out in minutes. By the end of the day, customers had asked to withdraw about $42 billion, roughly a quarter of the bank’s deposits.
SVB could not raise cash fast enough. It had not tested its ability to borrow from the Fed’s discount window and lacked collateral ready to pledge. Overnight, management told regulators it expected more than $100 billion more to leave on 10 March. California’s closure order said the bank ended the day with a negative cash balance.
2023
The announcement that started it Risk
After the market closed, SVB Financial Group told investors it had sold almost all of its $21 billion available-for-sale portfolio at a $1.8 billion after-tax loss and planned to raise $2.25 billion in new stock. The aim was to reposition its balance sheet as clients burned through cash.
Instead, the message heard by markets was that the bank needed capital. The same evening the crypto-focused Silvergate Bank announced it would wind down, adding to nerves about deposit-heavy niche lenders.
Rates rise and the hole grows Risk
The Federal Reserve began raising interest rates in March 2022 to fight inflation. The market value of SVB’s long-dated, low-yield bonds fell, and by the end of 2022 its unrealized losses on securities were about $15 billion, roughly equal to its equity. At the same time, venture funding slowed and startups drew down their deposits.
Supervisors issued findings on SVB’s risk management but did not force it to cut its interest-rate exposure. The bank went without a chief risk officer for much of the year and removed hedges as rates rose.
2021
Deposits triple in a tech boom Risk
Low rates and a venture-capital boom poured money into startups, and they parked it at SVB. The group’s assets grew 271% between the end of 2018 and the end of 2021, against 29% for the banking industry, according to the Fed. With few loans to make, SVB put much of the cash into government-backed mortgage securities with a weighted-average duration of about six years.
A 2018 law, the Economic Growth, Regulatory Relief and Consumer Protection Act, had raised the threshold for the strictest US bank rules from $50 billion to $250 billion of assets, and SVB grew through the lighter tier.
A bank for startups Event
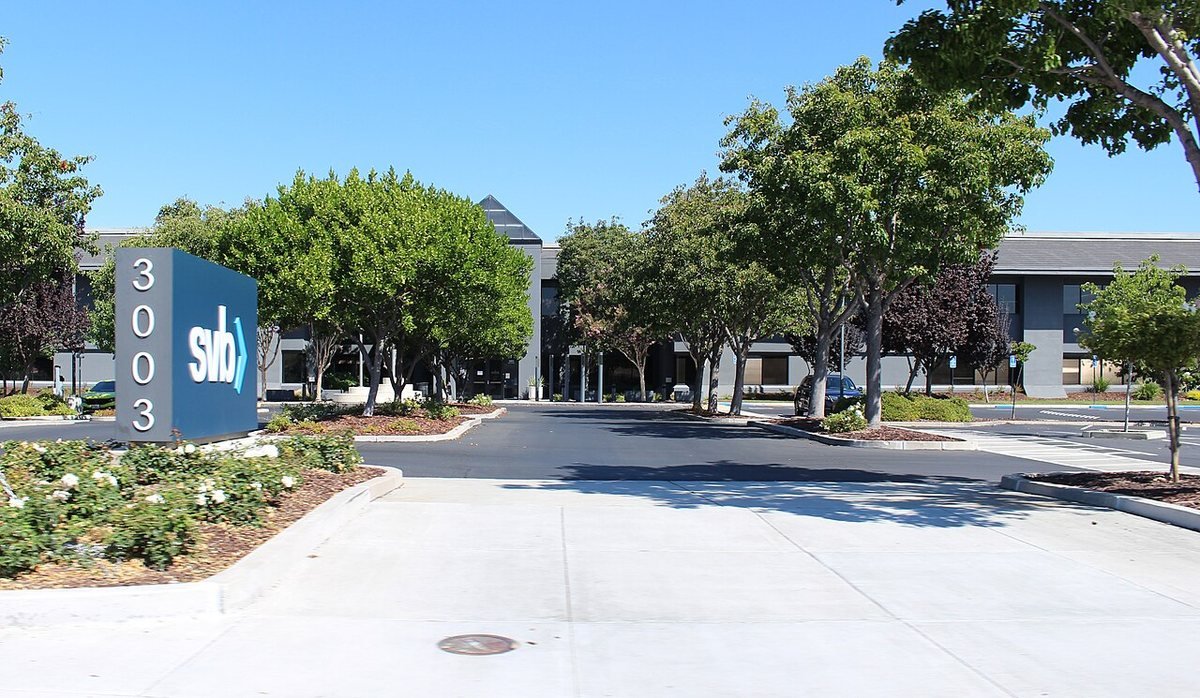
Silicon Valley Bank was founded in 1983 to bank companies other lenders found too risky: startups backed by venture capital. Over four decades it became the bank for much of the US tech ecosystem, offering loans, deposits and services to founders and their investors, and later expanding to the UK, Israel, India and China.
The 48 Hours, Step by Step
How a capital plan meant to reassure became the trigger.
Pick a moment. How much of SVB’s money had gone?
The meter shows cumulative outflows as a share of the $175.4 billion in deposits SVB held at the end of 2022. The final step is what management expected, not what was paid.
How Did a $209 Billion Bank Fail So Quickly?
Assets are not cash. A bank can own valuable securities and still be unable to pay depositors who all want their money today.
1. Interest-rate risk: the bonds lost value
SVB took in deposits at near-zero rates in 2020 and 2021 and bought long-dated Treasuries and mortgage securities. When the Fed raised rates from March 2022, newly issued bonds paid more, so SVB’s older ones fell in market value. Held to maturity, those losses would never be realised. Sold to meet withdrawals, they were real, and they were about as large as the bank’s capital.
2. Deposit concentration: one ecosystem, one mood
SVB’s customers were startups, venture funds and their founders. When venture funding slowed in 2022 they all burned cash at once, draining deposits. When fear spread in March 2023, the same investors gave the same advice to hundreds of companies at the same time.
3. Uninsured deposits: a reason to be first
With about 94% of deposits above the $250,000 limit, almost every customer stood to lose if the bank failed. That created a classic first-mover problem: each depositor was rational to leave before others drained the cash, even though everyone leaving guaranteed the failure.
4. Management and supervision
The Fed’s 2023 review found SVB’s board and managers failed at basic risk management and that supervisors were too slow. Its contingency funding plan had not been tested, and it was not ready to borrow from the Fed’s discount window at the speed the run required. The 2026 review went further, saying staff knew of the vulnerabilities by March 2022.
Pick a balance. How much was at risk before the 12 March rescue?
FDIC insurance covers $250,000 per depositor, per bank, per ownership category. The meter shows the uninsured share before regulators protected every SVB depositor.
The Numbers Behind the Collapse
From FDIC and Federal Reserve statements. Assets are not deposits, requests are not completed transfers, and a planned raise is not cash received.
| Figure | Value | What it measures |
|---|---|---|
| Total assets | ~$209bn | Bank balance sheet, 31 Dec 2022 (FDIC) |
| Total deposits | ~$175.4bn | All deposits, 31 Dec 2022 (FDIC) |
| Uninsured share | ~94% | Deposits above $250,000, end-2022 (Fed) |
| Unrealized securities losses | ~$15bn | Market value below book, end-2022, mostly held-to-maturity |
| Securities sold | ~$21bn | Available-for-sale portfolio, announced 8 Mar 2023 |
| After-tax loss | ~$1.8bn | Realised on that sale |
| Planned capital raise | $2.25bn | Announced 8 Mar; never completed |
| Withdrawal requests | ~$42bn | Requested on 9 Mar (DFPI); Fed: over $40bn left |
| Expected outflows | $100bn+ | 10 Mar forecast by management; not paid |
| First Citizens purchase | ~$72bn | Assets bought at a $16.5bn discount, 26 Mar |
| Left in receivership | ~$90bn | Securities and other assets kept by the FDIC |
| Special assessment | ~$16.3bn | Charged to banks to cover SVB and Signature, Nov 2023 |
In 2023 the SVB run was widely called the first ‘Twitter-fuelled’ bank run, and the Fed’s own first review said social media and a concentrated, networked depositor base had sped it up. The Fed-commissioned Starling review in September 2026 challenged that account. An analysis by Charles River Associates found no evidence that social media triggered or accelerated the deposit flight: 96% of social media activity about the run appeared only after SVB’s failure was already inevitable.
What did change the speed was the customer base and the technology. Founders and venture partners texted, called and emailed each other directly, and online banking let a company move millions in minutes rather than queueing at a branch. Faster communication shortened the time to respond to weaknesses that had built up over years; it did not create them.
Who Was Involved
Silicon Valley Bank
Santa Clara lender to startups and VC funds since 1983; CEO Greg Becker from 2011. Now a division of First Citizens.
California DFPI
Chartered SVB and closed it on 10 March 2023, appointing the FDIC as receiver.
Federal Reserve
Supervised SVB through the San Francisco Fed. Reviewed itself in April 2023 and again via Starling in 2026.
FDIC
Ran the bridge bank, sold it to First Citizens and is suing 17 former SVB officers and directors.
First Citizens
Raleigh, North Carolina bank that bought about $72 billion of SVB assets at a $16.5 billion discount.
SVB Financial Group
Holding company that filed for Chapter 11 on 17 March 2023 and lost its $1.71 billion deposit claim in August 2026.
What SVB’s Collapse Meant for Indian Startups
SVB banked many Indian-founded and India-focused startups that had incorporated in the US to raise venture money. India’s then Minister of State for IT, Rajeev Chandrasekhar, said in March 2023 that more than $1 billion attributable to Indian startups was stuck at SVB when it failed, calling that a conservative estimate. After consulting more than 460 startups, he said about $250 million had been moved to banks in Gujarat’s GIFT City within days, and urged founders to use the Indian banking system rather than complex cross-border set-ups.
The 12 March US guarantee meant that money was not lost. The lasting lesson for founders everywhere was treasury management: spread cash across banks, use sweep accounts and money-market funds, and know which balances are insured.
What Changed After SVB Failed
Bank Term Funding Program
Loans against bonds at par, March 2023 to 11 March 2024, so banks did not have to sell at a loss.
Special assessment
About $16.3 billion charged mainly to large banks from 2024 to refill the deposit insurance fund.
Discount window
Regulators now press banks to pre-pledge collateral and test emergency borrowing before they need it.
Five Fed regions
October 2026 overhaul gives one regional leader responsibility for acting on problems quickly.
Lawsuits
FDIC v. 17 former officers and directors, filed January 2025 and allowed to proceed in October 2025.
Diversification
Companies now spread large balances across several banks and insured sweep products.
Lessons From the 48-Hour Run
- Assets are not liquidity: valuable bonds do not pay depositors until they are sold or pledged.
- Manage rates across the cycle: long assets funded by flighty deposits are a bet on rates staying low.
- Concentration is correlation: customers who share investors and advice will move together.
- Test the emergency plan: a contingency plan only counts if the bank can execute it in hours.
- Supervisors must act, not just note: the 2026 review found the risks were known a year early.
Explore More Timelines
People Also Ask
Frequently Asked Questions
Conclusion: A Crisis Built Over Years, Triggered in Hours
Silicon Valley Bank’s decisive 48 hours began with a securities sale and a capital plan, escalated into about $42 billion of withdrawal requests and ended with regulators taking the keys. But the conditions that made the run fatal, unhedged interest-rate risk, a deposit base that was almost entirely uninsured and concentrated in one industry, and supervisors who saw the danger without forcing action, had been building since 2020.
Three and a half years on, the courts are assigning responsibility and the Fed is rebuilding how it supervises banks. The core lesson has not changed: in a digital banking system, confidence can disappear faster than a bank can turn its assets into cash.
Related AiTimeline Stories
⚠️ Editorial Note
Figures come from the FDIC, the Federal Reserve’s April 2023 review and September 2026 independent review, the California DFPI and court reporting. The $42 billion figure is withdrawal requests on 9 March 2023; the $100 billion figure for 10 March was management’s expectation, not money withdrawn. The FDIC lawsuit against former SVB officers and directors makes allegations that have not been proven at trial. Developments are current to 14 October 2026. This is general information, not investment or banking advice.
Sources & further reading
Every dated entry above was checked against these references. Last reviewed 14 October 2026.
- Federal Reserve: Review of the Federal Reserve's Supervision and Regulation of Silicon Valley Bank (April 2023)
- Federal Reserve: Evolution of Silicon Valley Bank (March 8 announcement, $40bn+ outflows on March 9, 94% uninsured deposits)
- FDIC: Creation of the Deposit Insurance National Bank of Santa Clara (10 March 2023)
- Treasury, Federal Reserve and FDIC: Joint Statement on the systemic-risk exception (12 March 2023)
- FDIC: First-Citizens Bank and Trust Company to assume deposits and loans of Silicon Valley Bridge Bank (26 March 2023)
- FDIC: Failed Bank Information for Silicon Valley Bank, Santa Clara, CA
- California DFPI: Review of the supervision and closure of Silicon Valley Bank (May 2023)
- Federal Reserve: Bowman speech on initial findings from the independent review of Silicon Valley Bank (18 September 2026)
- Banking Dive: FDIC sues 17 ex-SVB executives and directors alleging gross negligence (17 January 2025)
- American Banker: FDIC won't have to return $1.71 billion to SVB creditors (September 2026)
- American Banker: Fed's Bowman unveils major overhaul of its bank supervision (October 2026)
- Business Today: Over $1 billion in deposits of Indian startups was stuck in SVB, says MoS IT Rajeev Chandrasekhar (16 March 2023)
Did Social Media Bring Down SVB?